Ron Thomas
General Manager
NMLS #184658
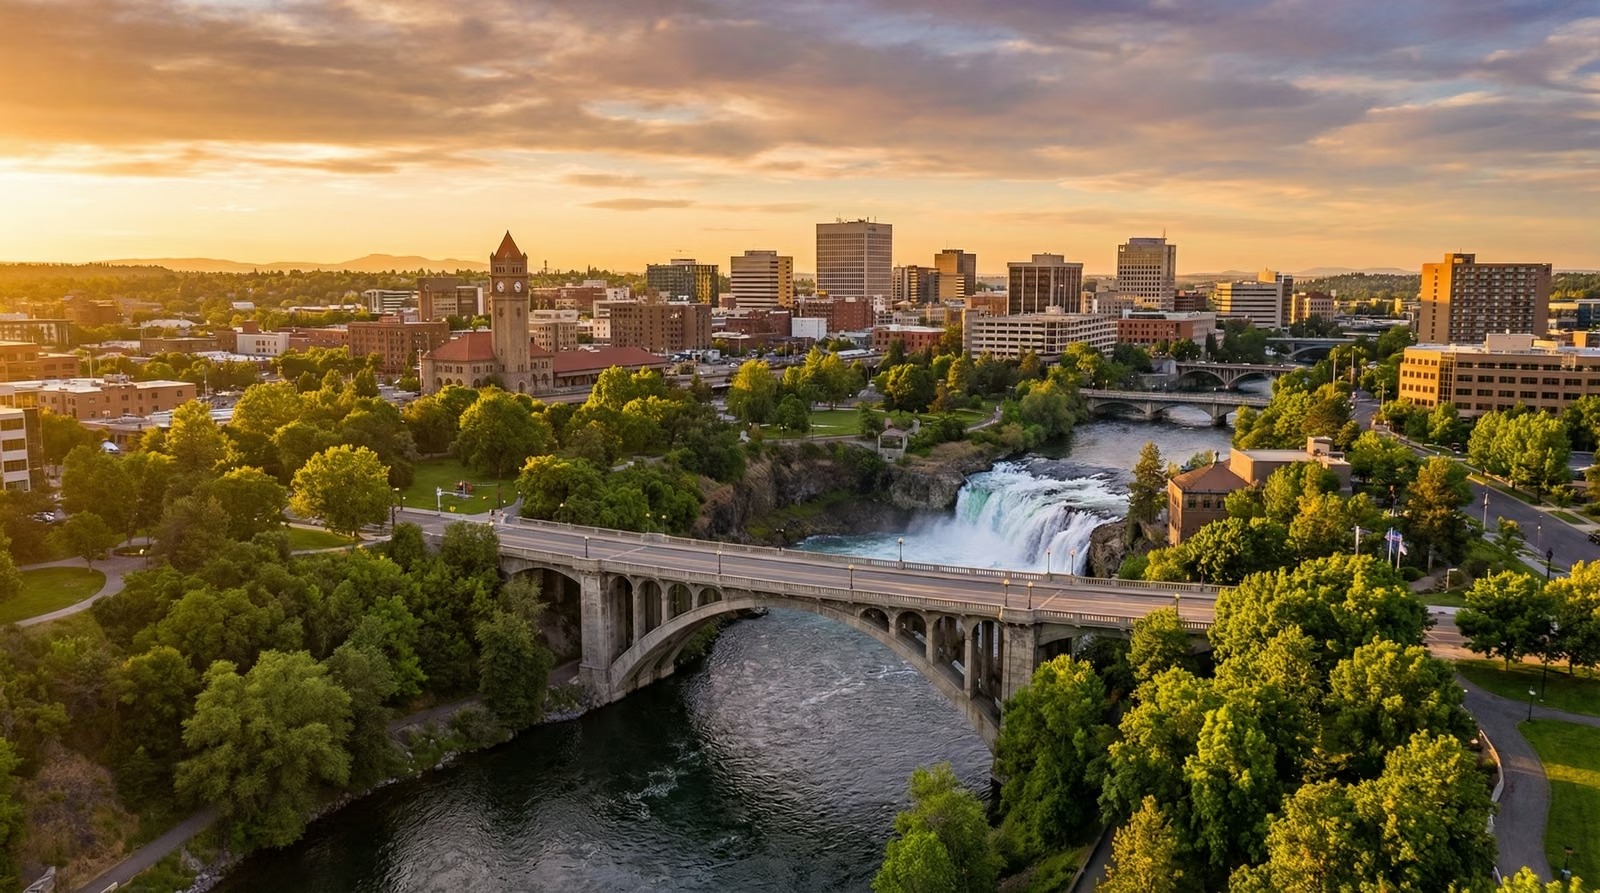
Local mortgage lending in Spokane County
Talk with a local loan officer about purchase, refinance, VA, FHA, conventional, and down payment assistance options.
Start here
Choose a starting point to explore information or connect with our Spokane team.
Start a home-purchase conversation with a local loan officer.
Get startedExplore FHA and Pathway DPA options for eligible first-time buyers.
Explore optionsLearn about VA purchase options for eligible veterans, service members, and surviving spouses.
Explore VA loansExplore refinance options with a loan officer based on your goals and circumstances.
Explore refinanceProgram eligibility and underwriting requirements apply.
Connect with a Q Home Loans loan officer serving Spokane County.
General Manager
NMLS #184658
Regional Manager
NMLS #190015
Senior Mortgage Loan Officer
NMLS #1394040
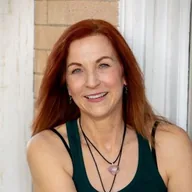
Senior Loan Officer
NMLS #1717034
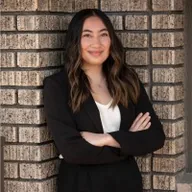
Loan Originator
NMLS #1870112
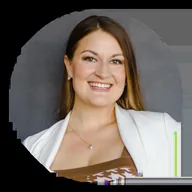
Loan Originator
NMLS #2320267
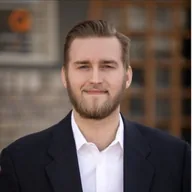
Loan Originator
NMLS #2098382
Loan Originator
NMLS #2369681
Mortgage Strategist | Sr. Loan Officer
NMLS #887456
Start with a conversation about your goals, the property, and the documentation you have available.
Choose a loan officer and use that officer's personal application path when you are ready.
Q Home Loans is a division of American Pacific Mortgage Corporation, NMLS #1850.
Discuss the purchase process and available program options before you begin an application.
Work with Marcus VogtLearn about VA home-loan options for a primary residence and the documentation that may be needed.
Work with Chad ThomasReview refinance options with a loan officer based on your current loan and your goals.
Work with Ron ThomasOur local office
Q Home Loans' Spokane branch is located at 1102 N Monroe St, serving the greater Spokane area with local mortgage lending services.
A conventional mortgage is a home loan that falls under the applicable conforming loan limit. Qualification requirements and mortgage insurance may apply.
Why in Spokane: A starting point for buyers evaluating home-financing options.
Explore Conventional LoansFHA loans are backed by the Federal Housing Administration and are designed to help borrowers who need more flexible qualification options.
Why in Spokane: A program to discuss when reviewing your qualification path.
Explore FHA LoansVA loans are backed by the Department of Veterans Affairs for eligible veterans, service members, and surviving spouses buying a primary residence.
Why in Spokane: For eligible military-connected buyers planning a primary residence.
Explore VA LoansUSDA loans are backed or issued by the U.S. Department of Agriculture for eligible borrowers and properties. Income and property requirements apply.
Why in Spokane: Property eligibility is determined for the specific address.
Explore USDA LoansJumbo options may be available when a home loan exceeds the applicable conforming loan limit for a higher-priced property.
Why in Spokane: A conversation for financing above the applicable conforming limit.
Explore Jumbo LoansEligible self-employed borrowers may have alternative documentation options, including qualification based on business bank statements and deposits rather than tax returns.
Why in Spokane: For a conversation about self-employed income documentation.
Explore Bank Statement LoansDSCR loans are investment-property options that may evaluate a property's income potential rather than relying primarily on personal income documentation.
Why in Spokane: For non-owner-occupied investment-property planning.
Explore DSCR LoansSpokane, WA
$393,000
Typical home value
Source: Zillow Home Value Index, September 2026
Local area notes for communities in the Spokane service area.
Area notes
An established Spokane area south of downtown.
Area notes
A Spokane neighborhood along the river corridor.
Area notes
A city east of Spokane within the broader service area.
Area notes
Communities west of Spokane.
Area notes
North Spokane communities with a range of housing styles.
Area notes
Historic Spokane neighborhoods near downtown.
Area notes
A nearby city within the Spokane-area service market.
Your down payment depends on the loan program, purchase price, property, and borrower qualifications. Conventional and FHA loans have different requirements, while eligible VA or USDA borrowers may have other options. Closing costs and prepaid expenses are separate from the down payment. Ask a Q Home Loans loan officer whether Pathway DPA is available for your situation, including its assistance repayment terms and underwriting requirements. Related: Explore Pathway DPA.
There is no single mortgage credit-score requirement that applies to every Washington homebuyer. Requirements vary by loan program and current lender underwriting guidelines. A Q Home Loans loan officer can review your credit history alongside income, debts, savings, and property details. Meeting a federal program's published minimum does not establish lender approval; additional program or lender requirements may apply to your application. Related: Learn about FHA loans.
The 2026 FHA loan limit for a single-unit home in Spokane County is $541,287, according to HUD's county mortgage-limit file. Spokane County uses the standard FHA floor, not the national high-cost ceiling. This is a loan limit, not a purchase-price limit or an approval amount. Your qualifying loan amount also depends on income, debts, credit, the property's appraisal, and current FHA and lender underwriting requirements. Related: Explore FHA loans.
The 2026 conforming loan limit for a single-unit home in Spokane County is $832,750, as listed in FHFA's official county table. The limit concerns loan size, not the home's purchase price or the amount a borrower qualifies to receive. Loans above the applicable conforming limit generally fall into jumbo financing. Credit, income, debts, assets, property details, and lender underwriting still determine available options. Related: Explore conventional loans.
You may be able to use a VA loan for a qualifying primary residence near Fairchild Air Force Base if you have eligible service or surviving-spouse status and meet VA and lender requirements. Being stationed near the base does not establish eligibility by itself. Your loan officer can review your Certificate of Eligibility, available entitlement, income, credit, occupancy plans, and the property's appraisal and condition before determining whether the purchase qualifies. Related: Explore VA home loans.
For homes in or around Cheney, Deer Park, and Nine Mile Falls, check USDA eligibility address by address rather than assuming an entire community qualifies. Enter the exact property address in the official USDA property eligibility map. A map result is not final approval: household income, repayment ability, primary-residence occupancy, property standards, and lender requirements also apply. USDA makes the final property eligibility determination after receiving a complete application. Related: Check the official USDA property eligibility map.
Timing depends on your home search, purchase contract, documentation, property, and underwriting requirements. After preapproval, you choose a home and negotiate an offer. An accepted offer leads to appraisal, title and insurance review, processing, and underwriting. Any outstanding conditions must be resolved before closing disclosures, signing, funding, and recording. Document requests, appraisal issues, title concerns, and changes to employment or finances can affect progress, so discuss the transaction's milestones with your loan officer. Related: Connect with a Q Home Loans loan officer.
Prequalification is an initial discussion of your goals, budget, income, assets, debts, and credit to estimate possible financing. Preapproval involves a loan application and verification of financial information, with underwriting review as applicable. It provides a more detailed, conditional assessment for shopping and making an offer. Neither replaces final loan approval, which still depends on the selected property, current financial information, and satisfaction of underwriting and closing conditions. Related: Discuss prequalification or preapproval.
Yes, if the loan officer holds active licenses in both Washington and Idaho and works through a lender authorized for the property location. Before comparing homes across the state line, ask the Q Home Loans team to confirm the officer's current licensing and program availability. You can also verify licensing through NMLS Consumer Access. Property-specific underwriting, title, insurance, and closing requirements may differ between the states. Related: Connect with a loan officer.
Eligibility depends on the loan program, borrower qualifications, property details, and current underwriting guidelines. A Q Home Loans loan officer can review income, employment, credit history, debts, assets, intended occupancy, and the property's type and location. Some programs also require military eligibility, household income review, or an eligible property address. Program availability and lender requirements can change, and all loans remain subject to underwriting approval. Related: Explore conventional loan requirements.
Sep. 16, 2026
Sep. 16, 2026
Sep. 28, 2026
Tell us about your home-financing goals and we will help you identify a next step.
Get Pre-ApprovedQ Home Loans · 1102 N Monroe St · Spokane, WA 99201 · (509) 216-3333