Homeowners on both sides of the Washington–Idaho state line have built meaningful equity over the past decade. According to the Federal Housing Finance Agency's House Price Index, home prices in the Spokane–Spokane Valley metro rose 126.9% from the second quarter of 2016 to the second quarter of 2026. In the Coeur d'Alene metro, prices rose 162.0% over the same period.
This report looks at how home values have changed across Spokane and North Idaho, what the data can—and cannot—tell an individual homeowner, and how a home equity line of credit (HELOC) or cash-out refinance may fit into a broader financing conversation.
Important: This report is educational and market-wide. The FHFA index measures average metro-area price change; it is not an appraisal or estimate of any individual property's value. Loan approval, terms, and availability depend on credit, property eligibility, equity, and underwriting requirements.
Key findings
- Spokane–Spokane Valley metro home prices rose 126.9% over 10 years and 29.1% over five years.
- Coeur d'Alene metro home prices rose 162.0% over 10 years and 33.3% over five years.
- From Q2 2025 to Q2 2026, Spokane prices were essentially flat while Coeur d'Alene prices rose 3.5%.
- Coeur d'Alene outpaced Spokane in every period measured in this report.
Home price growth by period
| Period | Spokane–Spokane Valley Metro | Coeur d'Alene Metro |
|---|---|---|
| 10 years (Q2 2016 to Q2 2026) | +126.9% | +162.0% |
| Since Q2 2019 | +68.9% | +90.7% |
| 5 years (Q2 2021 to Q2 2026) | +29.1% | +33.3% |
| Past year (Q2 2025 to Q2 2026) | 0.0% (flat) | +3.5% |
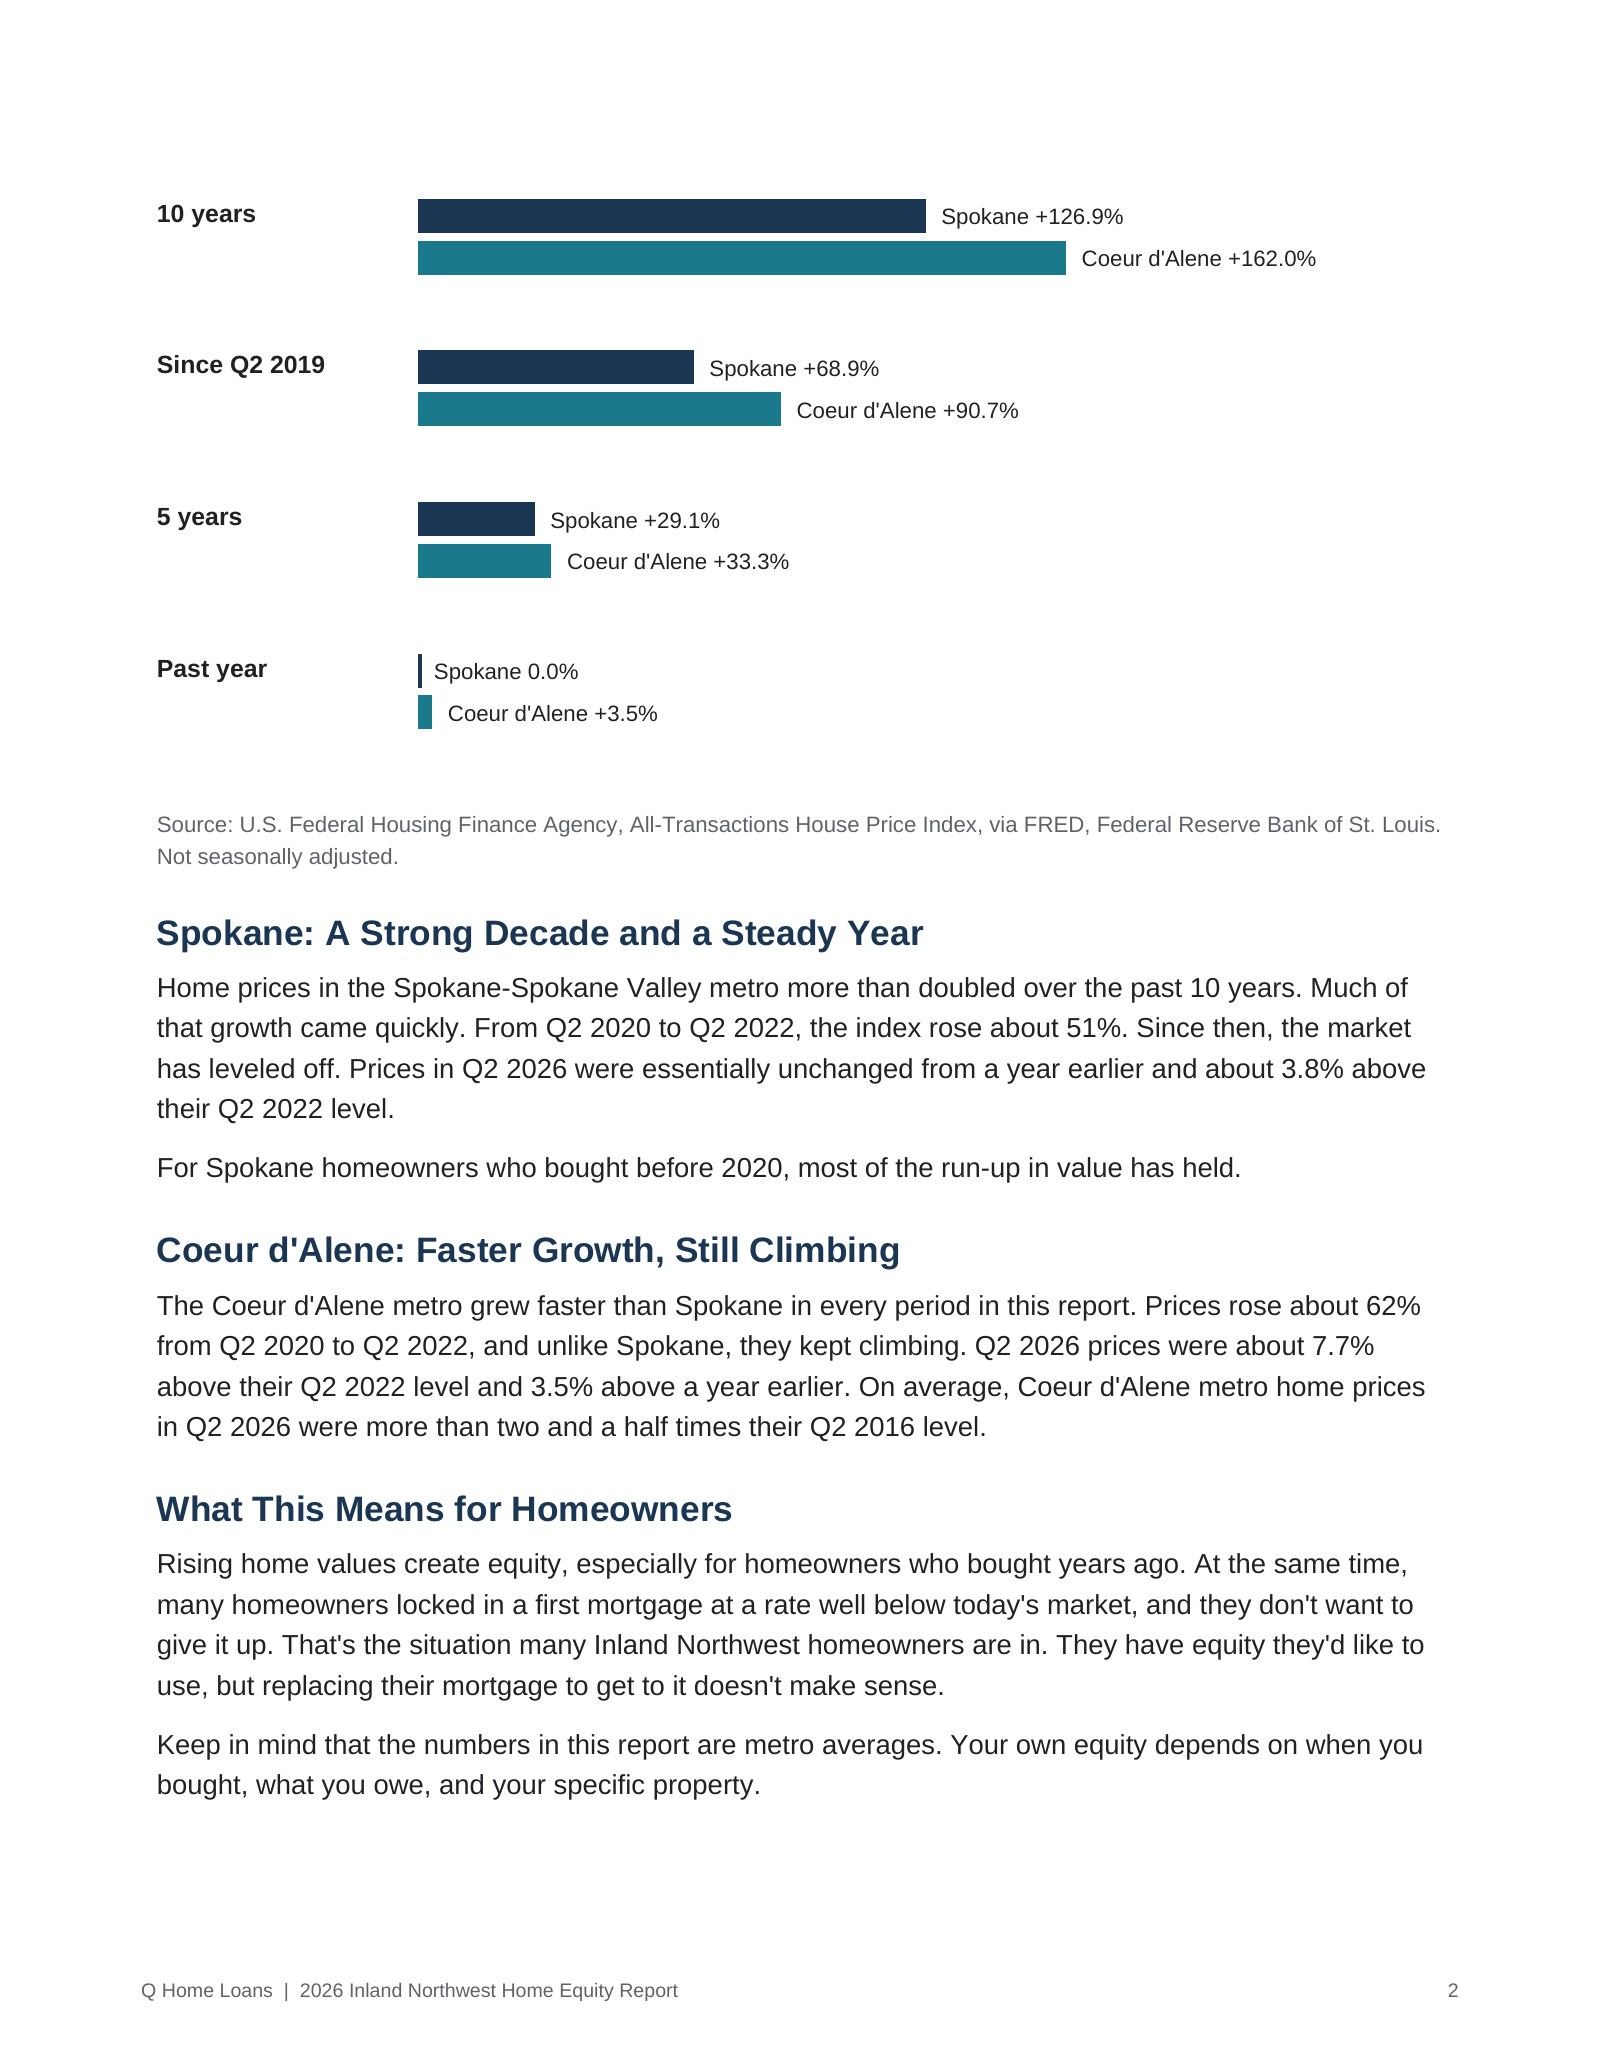
Source: U.S. Federal Housing Finance Agency, All-Transactions House Price Index, via FRED, Federal Reserve Bank of St. Louis. Data are not seasonally adjusted.
Spokane: a strong decade and a steady year
Home prices in the Spokane–Spokane Valley metro more than doubled over the past decade. Much of the growth came quickly: from Q2 2020 to Q2 2022, the index rose about 51%. Since then, the market has leveled off. Prices in Q2 2026 were essentially unchanged from a year earlier and about 3.8% above their Q2 2022 level.
For Spokane homeowners who bought before 2020, the report shows that much of the prior run-up in value has held. That does not mean every home changed by the same amount. Neighborhood, property condition, improvements, lot characteristics, and recent comparable sales can all affect an individual home's current value.
Coeur d'Alene: faster growth, still climbing
The Coeur d'Alene metro grew faster than Spokane in every period in this report. Prices rose about 62% from Q2 2020 to Q2 2022 and continued rising afterward. Q2 2026 prices were about 7.7% above their Q2 2022 level and 3.5% above a year earlier.
On average, Coeur d'Alene metro home prices in Q2 2026 were more than two and a half times their Q2 2016 level. As with Spokane, that is a metro-level measure—not a valuation of a specific home.
What this means for homeowners
Rising values may create equity, especially for owners who purchased years ago. At the same time, many homeowners have a first-mortgage rate they prefer to keep. Replacing that mortgage may not make sense simply to access funds.
Before making a financing decision, it helps to separate two questions:
- What is the home likely worth today? A market report can provide context, while a lender, real-estate professional, or appraiser can help assess a particular property when needed.
- How much usable equity is available? That depends on the home's value, current loan balance, the new financing structure, and program requirements.
Track your home's value and equity with Homebot for a no-cost estimate and ongoing market context. Homebot estimates are informational and are not appraisals.
Using equity without replacing a first mortgage
Homeowners generally have two main ways to access equity:
- A cash-out refinance replaces the existing mortgage with a new, larger loan.
- A home equity line of credit (HELOC) is a separate loan secured by the home, allowing the first mortgage to remain in place.
If keeping an existing first mortgage is important, a HELOC may be worth discussing. A cash-out refinance may be a different fit depending on the overall mortgage, goals, costs, and qualification.
A HELOC is secured by the home. It is important to understand repayment terms, any variable-rate features, fees, and how a new payment fits into the household budget before moving forward.
Digital HELOC prequalification
Q Home Loans offers a digital HELOC through American Pacific Mortgage. Eligible homeowners may be able to see a preliminary prequalification result online using a soft credit check, and the online application is designed to take about 5 to 10 minutes. Income may be verified through automated third-party systems.
Prequalification is not a loan approval or commitment to lend. Final approval depends on credit, income, property, title, and underwriting review. For a traditional HELOC, a cash-out refinance, or a conversation about what fits your situation, connect with Marcus Vogt.
Methodology and limitations
This report uses the U.S. Federal Housing Finance Agency's All-Transactions House Price Index for the Spokane–Spokane Valley, WA metro and the Coeur d'Alene, ID metro, retrieved through the Federal Reserve Bank of St. Louis' FRED database. The index is estimated using sales prices and appraisal data and is not seasonally adjusted.
The percentage changes compare second-quarter index values using Q2 2026 data released August 25, 2026. The index measures average price change across each metro and does not reflect the value of an individual home. Q Home Loans may update this report as new data are released.
Frequently asked questions
How much have Spokane home values increased?
According to the FHFA House Price Index, Spokane–Spokane Valley metro home prices rose 126.9% from Q2 2016 to Q2 2026 and 29.1% over the prior five years. Prices were essentially flat from Q2 2025 to Q2 2026.
How much have Coeur d'Alene home values increased?
Coeur d'Alene metro home prices rose 162.0% over the same 10 years and 33.3% over the prior five years. Prices rose 3.5% from Q2 2025 to Q2 2026.
Can I access equity without refinancing my first mortgage?
A HELOC is a separate loan secured by the home, so the current first mortgage can remain in place. A cash-out refinance replaces the existing mortgage with a new one. The right approach depends on individual circumstances and qualification.
Does checking a digital HELOC prequalification affect credit?
The preliminary prequalification described in this report uses a soft credit check. A full application may involve a hard credit inquiry. Ask about the credit process before you apply.
About the report
Download the complete 2026 Inland Northwest Home Equity Report (PDF).
Disclosure: Marcus Vogt, NMLS #1394040, is licensed in Washington and Idaho. Q Home Loans is a division of American Pacific Mortgage Corporation, NMLS #1850. HELOCs are secured by your home, and failure to repay could result in loss of the home. All loans are subject to credit approval, property eligibility, and underwriting guidelines. Product features and availability are subject to change. Market data are for informational purposes only and are not an appraisal or tax advice.