Chad Thomas
Regional Manager
NMLS #190015
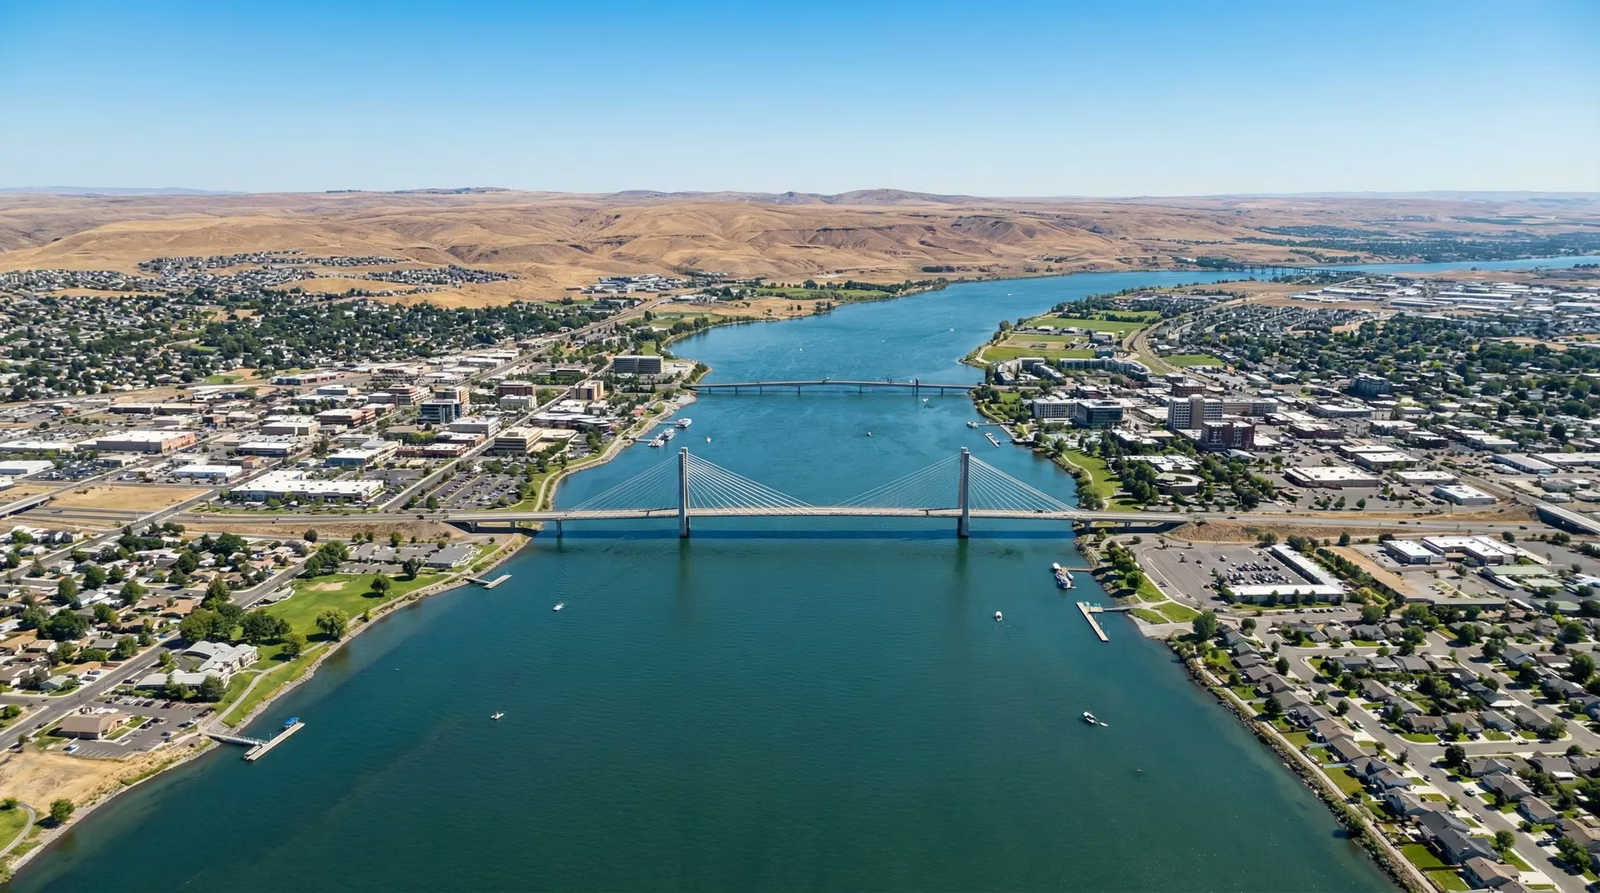
Home lending for Kennewick, Pasco & Richland
Talk with a local loan officer about purchase, refinance, VA, FHA, conventional, and down payment assistance options in Kennewick, Pasco, and Richland.
Start here
Choose a starting point to explore information or connect with our Tri-Cities team.
Start a home-purchase conversation with a local loan officer.
Get startedExplore FHA and Pathway DPA options for eligible first-time buyers.
Explore optionsLearn about VA purchase options for eligible veterans, service members, and surviving spouses.
Explore VA loansExplore refinance options with a loan officer based on your goals and circumstances.
Explore refinanceProgram eligibility and underwriting requirements apply.
Connect with a Q Home Loans loan officer serving the Tri-Cities.
Regional Manager
NMLS #190015
Mortgage Strategist | Sr. Loan Officer
NMLS #887456
Start with a conversation about your goals, the property, and the documentation you have available.
Choose a loan officer and use that officer's personal application path when you are ready.
Q Home Loans is a division of American Pacific Mortgage Corporation, NMLS #1850.
Discuss the purchase process and available program options before you begin an application.
Work with Chad ThomasLearn about VA home-loan options for a primary residence and the documentation that may be needed.
Work with Chad ThomasReview the income documentation that may be considered for your application.
Work with Cliff BarnesOur local office
Q Home Loans - Tri-Cities
8202 W Quinault Ave, Suite B
Kennewick, WA 99336
Branch NMLS #2483287
Q Home Loans' Tri-Cities branch serves Kennewick, Pasco, Richland, and the broader Tri-Cities region with home-loan conversations.
A conventional mortgage is a home loan that falls under the applicable conforming loan limit. Qualification requirements and mortgage insurance may apply.
Why in Tri-Cities: A starting point for buyers evaluating home-financing options.
Explore Conventional LoansFHA loans are backed by the Federal Housing Administration and are designed to help borrowers who need more flexible qualification options.
Why in Tri-Cities: A program to discuss when reviewing your qualification path.
Explore FHA LoansVA loans are backed by the Department of Veterans Affairs for eligible veterans, service members, and surviving spouses buying a primary residence.
Why in Tri-Cities: For eligible military-connected buyers planning a primary residence.
Explore VA LoansUSDA loans are backed or issued by the U.S. Department of Agriculture for eligible borrowers and properties. Income and property requirements apply.
Why in Tri-Cities: Property eligibility is determined for the specific address.
Explore USDA LoansJumbo options may be available when a home loan exceeds the applicable conforming loan limit for a higher-priced property.
Why in Tri-Cities: A conversation for financing above the applicable conforming limit.
Explore Jumbo LoansEligible self-employed borrowers may have alternative documentation options, including qualification based on business bank statements and deposits rather than tax returns.
Why in Tri-Cities: For a conversation about self-employed income documentation.
Explore Bank Statement LoansDSCR loans are investment-property options that may evaluate a property's income potential rather than relying primarily on personal income documentation.
Why in Tri-Cities: For non-owner-occupied investment-property planning.
Explore DSCR LoansKennewick, WA
$428,000
Typical home value
Source: Zillow Home Value Index, September 2026
Richland, WA
$463,000
Typical home value
Source: Zillow Home Value Index, September 2026
Pasco, WA
$416,000
Typical home value
Source: Zillow Home Value Index, September 2026
Local area notes for communities in the Tri-Cities service area.
Area notes
A Tri-Cities area with outdoor trails and newer construction.
Area notes
A Kennewick community with parks and recreation.
Area notes
A riverfront area in the Tri-Cities.
Area notes
A Kennewick area with residential communities.
Area notes
A city within the Tri-Cities service area.
Area notes
A Pasco-area residential community.
For 2026, HUD lists a single-unit FHA mortgage limit of $541,287 in Benton County and $541,287 in Franklin County. These are the county limits for a home with a single dwelling unit, not a purchase-price cap or a promise of qualification. Your eligible loan amount also depends on income, debts, credit, appraisal, and FHA and lender requirements. Related: Explore FHA loans.
For 2026, FHFA's county table lists a single-unit conforming loan limit of $832,750 in Benton County and $832,750 in Franklin County. This limit concerns the mortgage amount, not the home's purchase price. Staying within it does not establish eligibility: credit, income, assets, debts, property details, and lender requirements still apply. Financing above the applicable limit may require a jumbo loan. Related: Explore conventional loans.
USDA property eligibility is determined by the exact address, not simply whether a listing says Pasco or West Richland. Enter the property address in USDA's official eligibility map rather than assuming an entire city or neighborhood qualifies. A potentially eligible location is only part of the review: household income, repayment ability, occupancy, property standards, and lender requirements also apply. USDA makes the final property determination after receiving a complete application. Related: Check the official USDA property eligibility map.
Have your employment offer or transfer letter, any employer relocation letter, recent pay stubs, wage tax forms, applicable tax returns, bank statements, and identification ready. Tell your loan officer about changes in employer, compensation, start date, or employment gaps. The documents required depend on your income type and loan program. An offer letter alone does not establish qualification; the lender must determine whether the income meets applicable underwriting requirements. Related: Connect with a Tri-Cities loan officer.
There is no single credit-score requirement that applies to every Tri-Cities mortgage. Requirements vary by loan program and lender, and a score alone does not establish eligibility. Payment history, outstanding debts, income, assets, and property details also matter. Review your credit reports for errors before applying, and ask your loan officer which current program and lender requirements apply to your circumstances. Lender rules may be stricter than federal program guidelines. Related: Learn about FHA loan options.
Your required down payment depends on the mortgage program, property, purchase price, and borrower qualifications. Conventional and FHA loans have different requirements, while military eligibility or an eligible rural address may make other programs worth discussing. Budget separately for closing costs and any reserves the lender requires. Ask your loan officer to review your available funds, acceptable funding sources, and current underwriting requirements rather than assuming an advertised minimum applies to you. Related: Review conventional loan options.
Pre-qualification is an initial discussion of your goals, income, assets, debts, and credit to estimate a possible budget. Pre-approval involves a loan application and verification of financial information, with underwriting review. It is a more detailed assessment, but any letter may include conditions. The property, appraisal, title, and updated borrower information still need review before closing. Neither step is a commitment that your loan will be funded.
Timing depends on finding a property, negotiating the purchase contract, completing inspections, obtaining the appraisal and title work, and satisfying underwriting conditions. Employment changes, missing documents, appraisal issues, or property repairs can affect the schedule. Closing also involves required disclosures, signing, final lender review, funding, and recording. Coordinate the contract's closing date with your loan officer and real estate agent; pre-approval does not establish a fixed closing schedule.
Eligible first-time buyers can ask about Pathway DPA, described on our Pathway DPA program page. APM's current Pathway DPA pairs an FHA loan with assistance provided through a repayable second mortgage. Availability, borrower eligibility, property requirements, and underwriting must be confirmed for your application. Ask about repayment obligations and the combined mortgage payment before deciding. Assistance does not remove the need to qualify for the underlying mortgage. Related: Learn about Pathway DPA.
Nov. 25, 2025
Nov. 11, 2025
Jan. 27, 2026
Tell us about your home-financing goals and we will help you identify a next step.
Get Pre-ApprovedQ Home Loans - Tri-Cities · 8202 W Quinault Ave, Suite B · Kennewick, WA 99336 · (509) 216-5555